Municipal Market Performance and Benchmark Rates: August continued the defining themes that have gripped fixed income markets all summer. Persistent inflation concerns, swelling deficits, geopolitical whiplash, and a new Federal Reserve regime pushed long-end yields to multi-decade highs before they retreated to close the month little changed.
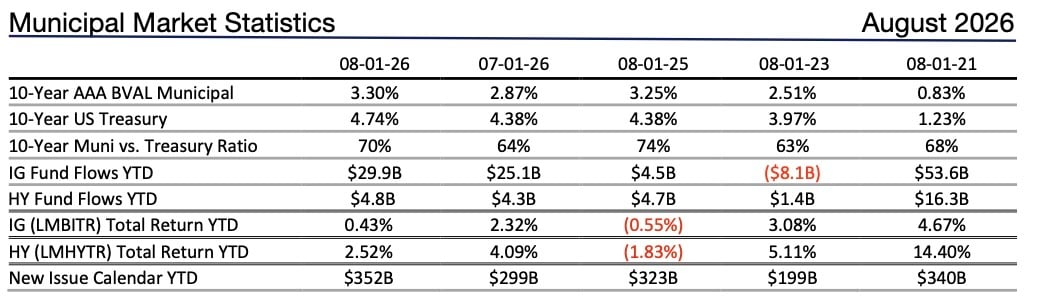
When the dust settled, the UST yield curve flattened slightly, with the 5-year note finishing 6 bps higher while the 10- and 30-year bonds ended the month largely unchanged. While U.S. Treasuries held relatively steady amid the intramonth volatility, the AAA Municipal Benchmark curve faced heavier headwinds, with 10- and 30-year muni yields rising 6 and 12 basis points, respectively. Despite the move higher in yields, both municipal indices rebounded into positive territory following last month’s capitulation. The Bloomberg Municipal Bond Index (LMBITR) eked out a +0.06% return in August, bringing its year-to-date gain to +0.49%. The Bloomberg High Yield Municipal Bond Index continued to outperform investment grade, returning +0.43% for the month and +2.96% YTD.
Mutual Fund Flows: Municipal fund flows remained overwhelmingly positive in August, continuing a remarkable run that has seen only two weekly net outflows all year. Funds closed August with their 19th consecutive week of inflows, while year-to-date inflows now stand at $67 billion (combining weekly and monthly reporting firms), the second-highest total on record for the comparable period. High-yield fund flows similarly reflected the broader positive momentum, with YTD inflows approaching $10 billion.
Primary Market Supply: New month, same story for municipal new-issue supply. The relentless pace of primary issuance accelerated in August, with tax-exempt supply approaching $60 billion — a 25% increase year-over-year and 50% above the trailing five-year August average. Despite strong overall municipal issuance, high-yield and non-rated supply remains anemic by comparison. While the current pipeline remains relatively lean, LCP has historically capitalized on Q4 seasonal supply spikes to secure compelling entry points.
Lind Capital Partners Municipal Non-Rated Market Commentary
Closing the Position, Not the File: A recent Bloomberg headline caught our attention. The story highlighted the turnaround efforts of Riverside Military Academy, a private military academy (grades 6-12), whose bonds we owned many years ago. The borrower defaulted last year on approximately $48 million of debt issued in 2017 and is now relying on an additional subordinate debt injection to stay afloat. The primary reason for the borrower’s default was a precipitous drop in enrollment during the COVID-19 pandemic, which never recovered. Prior to the pandemic, we had owned this credit for almost a decade and the bonds performed well. However, observing the negative credit impacts and very challenging path to recovery, we divested our position in 2021. Part of our credit-intensive strategy is maintaining an ongoing knowledge base of credits in our target sectors, even those we have sold. We spend significant time and energy understanding a borrower before committing capital, an intellectual investment that retains value even after a position leaves our portfolios. We continue to follow many of our former holdings, monitoring financial performance, management decisions, changes to the underlying business, and capital market activity. Over time, the new information we gather may confirm the concerns that led to divestiture or result in our reconsidering our prior assessment.
Coincidentally, around the same time we noted the Riverside Academy article, we found ourselves re-engaging with another former portfolio holding that we sold during roughly the same period. Similarly, we owned this well-performing credit for several years before COVID-19 induced credit stress prompted us to divest the position. However, over the years we maintained close surveillance and observed stabilizing fundamental credit conditions. The market presented an opportunity to reinvest in this credit at prices that we believe significantly undervalued the credit improvements. Our history with the borrower greatly contributed to our ability to understand their current position and gain conviction to reenter the position.
For Lind Capital, the comparison of these two credits illustrates a critical feature of our credit process: divesting a position does not necessarily result in our closing the credit file. Credit analysis is not about permanently labeling a borrower “good or bad.” It is about continually assessing credit fundamentals and the relationship between risk and return at a particular point in time. Fundamentals change. Management teams change. Capital structures and financial resources evolve. Asset values rise and fall. And perhaps most importantly, market prices can change dramatically. There is significant value in institutional memory. When we revisit a credit years later, we are not starting from scratch. We know the issues that concerned us, the assumptions underlying our original analysis and how events ultimately unfolded. That history provides valuable context when evaluating a former credit anew and helps us determine the appropriate risk/return given current conditions.
At this point, we will remain interested bystanders of Riverside Academy. And while these two credits appear to be traveling in opposite directions, they illustrate the same investment discipline: continually reassessing the creditworthiness of a borrower rather than remaining anchored to an earlier conclusion. Our history with our portfolio credits provides invaluable context. It is never a permanent verdict.
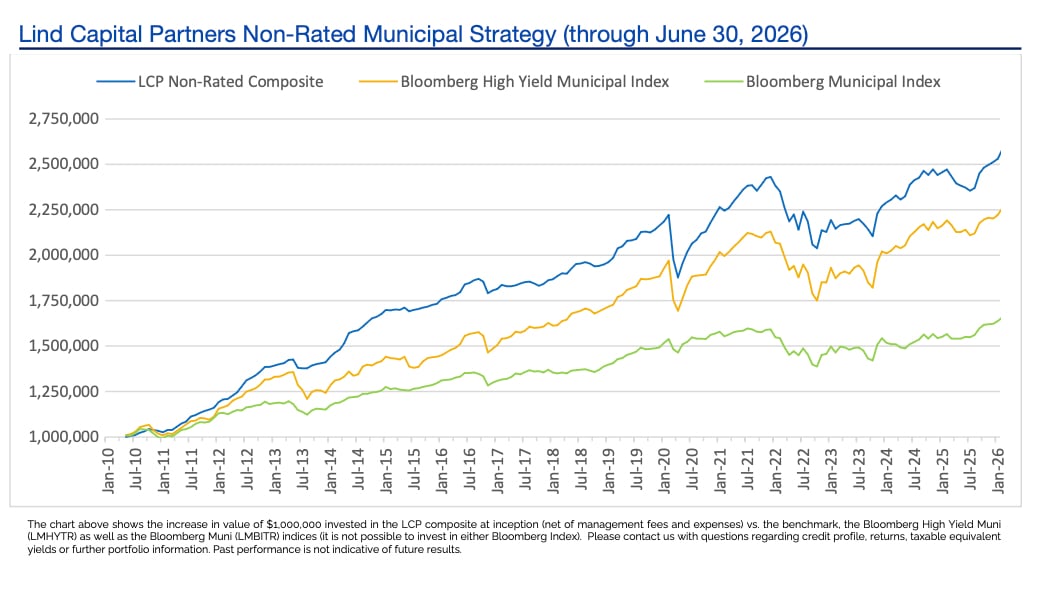
The chart above shows the increase in value of $1,000,000 invested in the LCP composite at inception (net of management fees and expenses) vs. the benchmark, the Bloomberg High Yield Muni (LMHYTR) as well as the Bloomberg Muni (LMBITR) indices (it is not possible to invest in either Bloomberg Index). Please contact us with questions regarding credit profile, returns, taxable equivalent yields or further portfolio information. Past performance is not indicative of future results.
Lind Capital Partners Municipal Market Charts